Introduction
The Securities and Exchange Board of India (‘SEBI’) issued certain clarifications for the transfer and transmission of shareholding among immediate relatives vide circular[i] (‘circular’).
The circular establishes the terms and conditions that would govern ownership transfers in intermediary corporations, including investment advisors, research analysts, and similar organisations. The circular clarifies that transfers of shares between immediate relatives will not be interpreted as a change in control. In other words, share transfers to immediate relatives do not signify a change in ownership or decision-making authority within the company. This provision aims to prevent abrupt or uncontrolled changes in the ownership or management of intermediaries, thereby ensuring the smooth functioning of the securities market.
As per reg. 2(1)I of the SEBI’s (Substantial Acquisition of Shares and Takeovers) Regulations, 2011 (‘Regulations’), spouses, parents, siblings, and children qualify as immediate relatives. Additionally, SEBI clarified that the transmission of shares, whether by inheritance or other means, to immediate relatives or other persons defined under the Regulations shall not be construed as a change in control.
Brief Summary of the Previous Circular on the Subject Matter
SEBI had previously issued another circular[ii] addressing the circumstances under which a change in ownership and shareholding of intermediaries does not amount to a change in control.
For corporate intermediaries that are unlisted entities, transmissions among immediate relatives were not considered a change in control. Similarly, for partnership firms with more than two partners, intra-partner transfers were not classified as a change in control.
However, in proprietary firms, the transfer or bequest of business or cash represented a change in control in proprietary enterprises, thus necessitating prior SEBI clearance and new registration. Additionally, it was also required that the ‘fit and proper person’ requirements set forth by SEBI be fulfilled by new entities or shareholders obtaining a controlling interest.
Key Provisions of the Circular
The primary clauses of the circular are delineated under the following categories:
1. Unlisted Body Corporate Intermediary: As per the circular, certain shareholding transmissions or transfers do not result in a change in control for unlisted body corporate intermediaries, particularly in the following scenarios:
Transfer Among Immediate Relatives: Transfers of shares between immediate relatives, as defined under the Regulations, do not constitute a change in control. The term ‘immediate relatives’ includes spouses, parents, siblings, and children of the person involved or their spouse.
Transfer of Shareholding: Similarly, the transfer of shares to an immediate relative through inheritance or any other legally recognised method does not result in a change in control.
2. Proprietary Firm Type Intermediary: In proprietary firms, the transfer or inheritance of business or capital leads to a change in legal ownership structure, which constitutes a change in control. Consequently, under the definition of a ‘change in control’, such a transmission or transfer requires:
Prior approval from SEBI
Fresh registration in the name of the legal heir or transferee
3. Partnership Firm Type Intermediary: The following provisions govern changes in partners and their ownership interest in partnership firms:
Transfer of Ownership Interest in a Partnership Firm:
If a SEBI-registered partnership firm has more than two partners, transfers among partners do not amount to a change in control.
However, if the firm has only two partners, the death of one partner dissolves the firm. In such a case, the induction of a new partner is considered a change in control, necessitating prior SEBI approval and fresh registration.
Transmission of Ownership Interest in a Partnership Firm:
If the partnership deed provides that, in the event of a partner’s death, the deceased partner’s legal heir(s) may be admitted as partners, the firm is reconstituted upon their admission.
However, such a transfer of ownership interest to legal heirs is not regarded as a change in control. Entities or shareholders acquiring controlling interest in the intermediary through share transfers must meet SEBI’s ‘fit and proper person’ criteria under sch. II of the SEBI (Intermediaries) Regulations, 2008.
Compliance with SEBI’s ‘Fit and Proper Person’ Criteria: Entities or shareholders acquiring a controlling interest in an intermediary through share transfers must satisfy the ‘fit and proper person’ criteria stipulated under Sch. II of the SEBI (Intermediaries) Regulations, 2008.
Conclusion
The circular has significant implications for intermediary organisations and the securities market. Exempting shareholding transactions among immediate relatives from being classified as a change in control ensures stability in ownership and management structures. This provision is particularly beneficial for family-owned intermediary businesses, as it eliminates the need for unnecessary regulatory approvals.
The circular strikes a balance between regulatory oversight and operational continuity by defining when shareholding transfers among immediate relatives do not require SEBI’s intervention. At the same time, it strengthens regulatory scrutiny for other ownership changes, ensuring compliance with the ‘fit and proper person’ criteria and thereby protecting market integrity and investor confidence.
However, where ownership changes involve a shift in legal structure or the induction of new partners, prior SEBI approval and fresh registration remain mandatory. This regulatory framework ensures that significant control transitions undergo rigorous assessment, safeguarding investor interests and market stability.
End Notes
[i] Circular SEBI/HO/MIRSD-PoD-1/P/CIR/2024/164, dt. 27.12.2024.
[ii] SEBI/HO/MIRSD/DOR/CIR/P/2021/42, dt. 25.03.2021.
Authored by Mohd Noumaan at Metalegal Advocates. The views expressed are personal and do not constitute legal opinions.
More Insights

22 Jun 2026
8
Min Read
Claim Admission Is Not Debt Acknowledgement: Supreme Court on RP’s Role & Limitation under the IBC
Can admission of a claim by a Resolution Professional extend limitation under section 18 of the Limitation Act? In Shankar Khandelwal v. Omkara Asset Reconstruction Pvt. Ltd., the Supreme Court answered this question in the negative, holding that claim admission during CIRP is merely a statutory claim-verification process and not an acknowledgement of debt. The ruling clarifies the RP’s non-adjudicatory role and reinforces important principles governing limitation under the IBC.

06 Apr 2026
5
Min Read
Minority Exit under S. 66: The Supreme Court on Fairness, Valuation, and the Limits of Judicial Scrutiny
The Supreme Court’s ruling in Pannalal Bhansali v. Bharti Telecom Ltd. clarifies the contours of fairness under Section 66 of the Companies Act, 2013. It reinforces a market-based approach to valuation, affirms the permissibility of DLOM, and underscores judicial deference in the absence of oppression, marking a significant shift in minority exit jurisprudence.
12 Nov 2025
14
Min Read
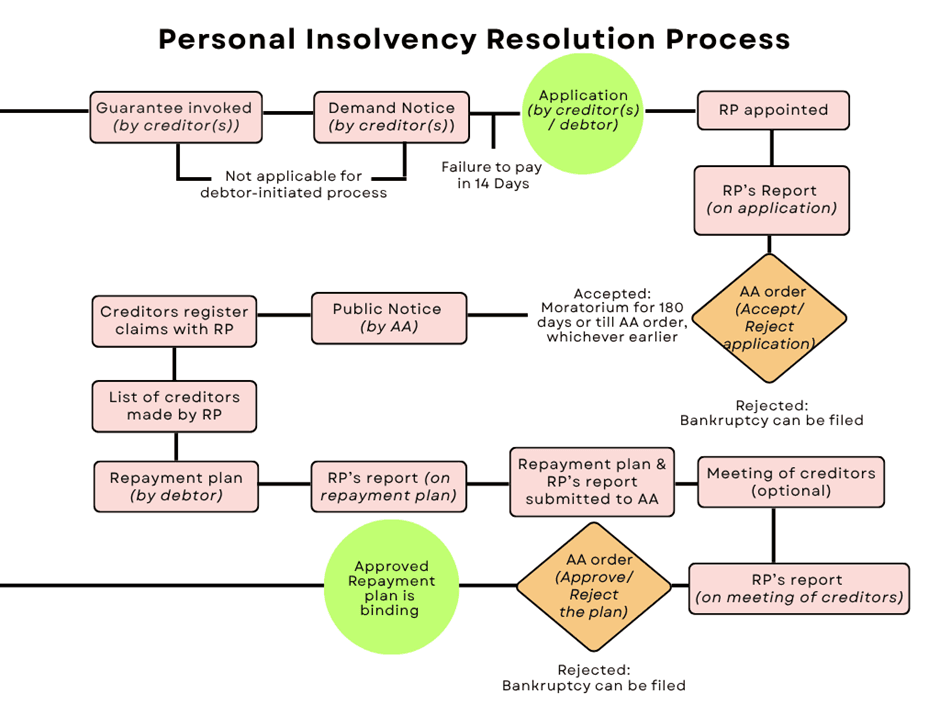
A Bird’s Eye View of the Insolvency and Bankruptcy Framework for Personal Guarantors under the IBC with Recent Judicial Developments
A concise overview of the personal insolvency and bankruptcy framework for personal guarantors under the IBC, with key NCLAT and NCLT rulings shaping the law. This piece explains initiation, moratoriums, repayment plans, creditor rights, bankruptcy triggers, and the 2025 Amendment Bill, offering a clear snapshot of the evolving jurisprudence and its practical implications for stakeholders.