Outbound investments made by Indian resident individuals and entities into foreign funds such as alternative investment funds, venture capital funds, etc., are regulated by the foreign exchange laws in India. While such law seeks to primarily regulate inward and outward fund flows in India, the interplay between the commercial exigencies to make investments and the legal regime presents a difficult and confusing terrain. This article seeks to simplify and summarise the legal provisions and their implications on such fund investments.
Introduction
Investments made into foreign funds by Indian resident individuals and entities are governed by the provisions of the Foreign Exchange Management Act, 1999 (‘FEMA’) and the Overseas Investment Rules, 2022 and the regulations and master directions issued along with such rules (collectively referred to as ‘OI Rules’).
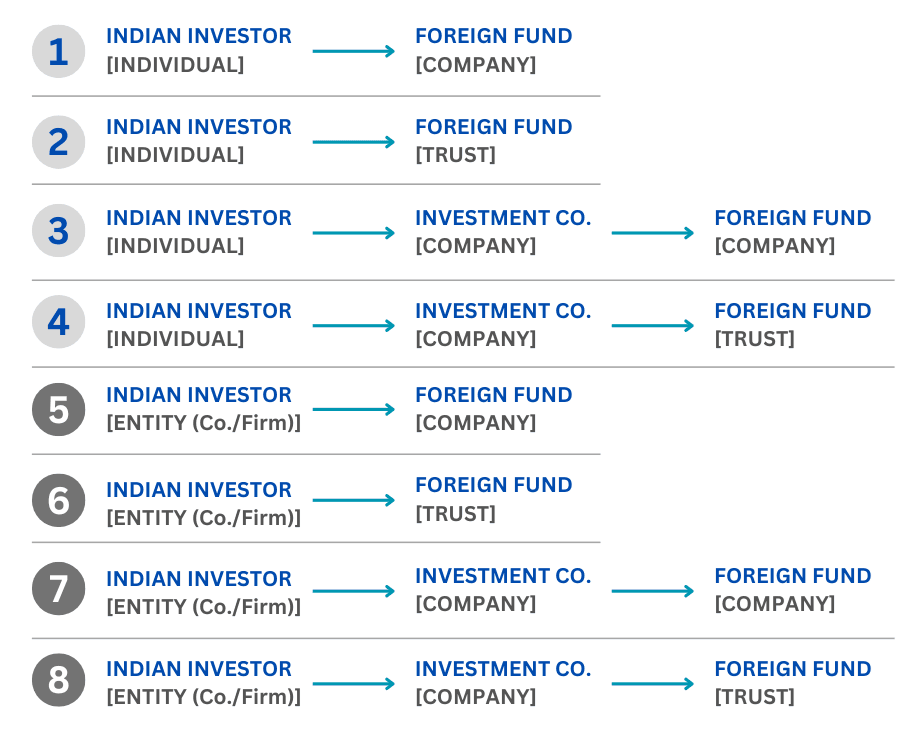
As noted above, the investments could be made either by resident individuals or by entities (including companies, partnership firms, LLPs, etc.). Additionally, the investee fund could be constituted either as a foreign company or a foreign trust. Further, the investment could be made indirectly into funds, i.e., investment in a foreign company which would in turn invest in the foreign fund.
These multiple investment scenarios can be tabulated as follows, and the implications under FEMA and OI Rules are being discussed thereafter.
I. Investments by Resident Individuals
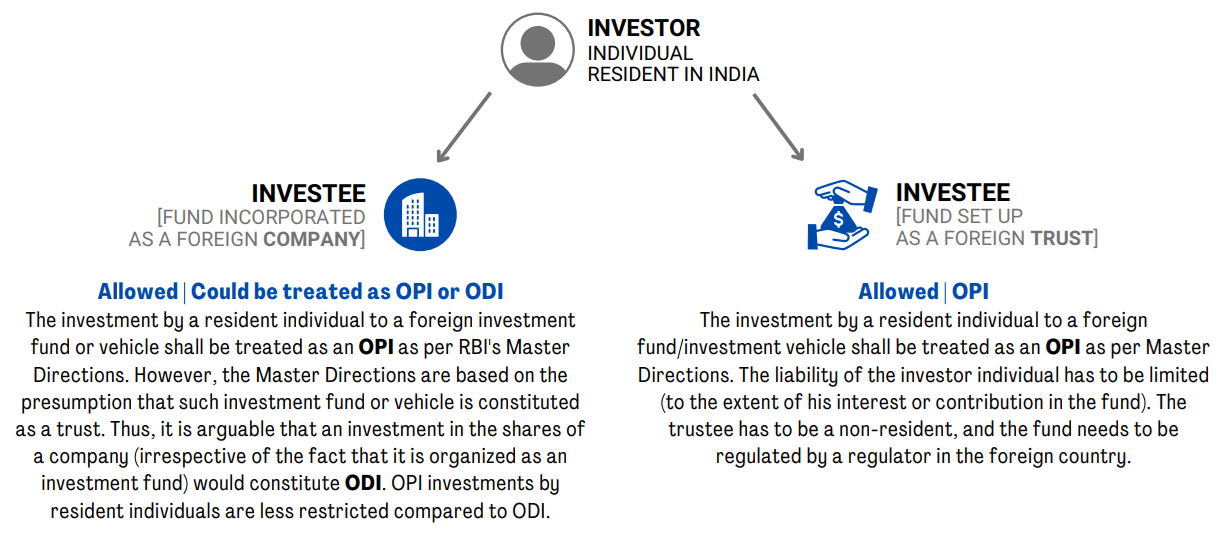
Resident individuals may make investments in foreign funds organised as a company or a trust. As per the OI Rules, such investment may be treated as an Overseas Portfolio Investment (‘OPI’). The implications under FEMA and OI Rules, in cases where the resident individual directly invests in the fund, have been diagrammed as follows:
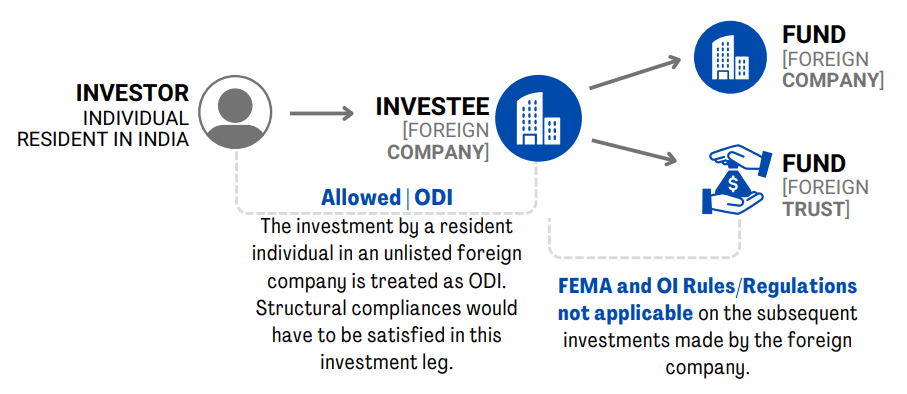
Investments, on the other hand, made by the resident individual through another foreign company (e.g., an investment company promoted by such individual), involve the following conclusions and implications under FEMA and OI Rules.
II. Investments by Indian entities (companies/partnership firms / LLPs)
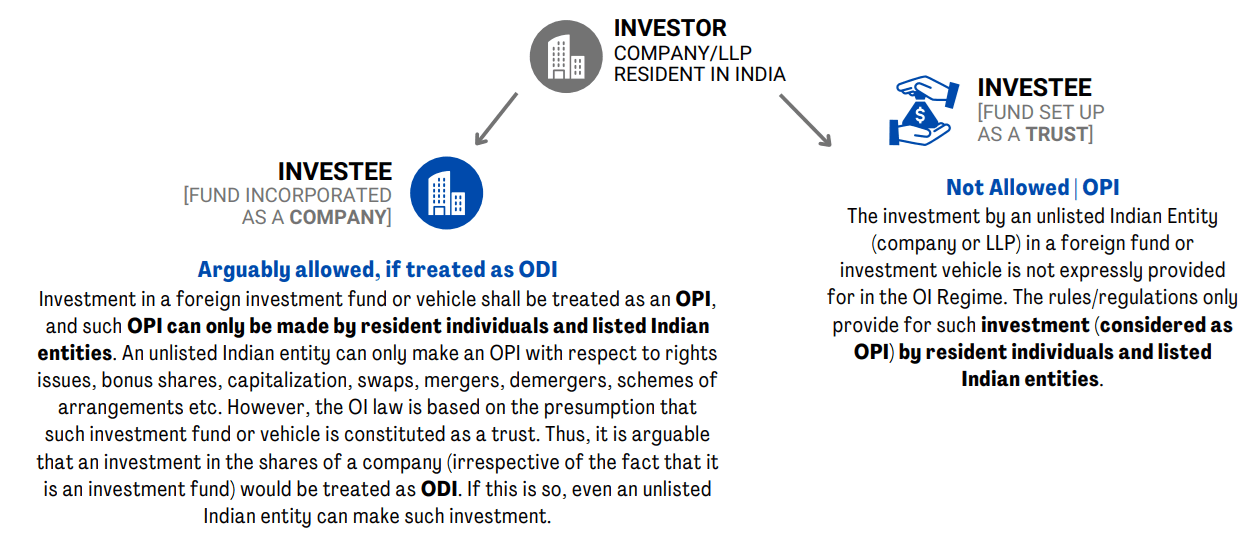
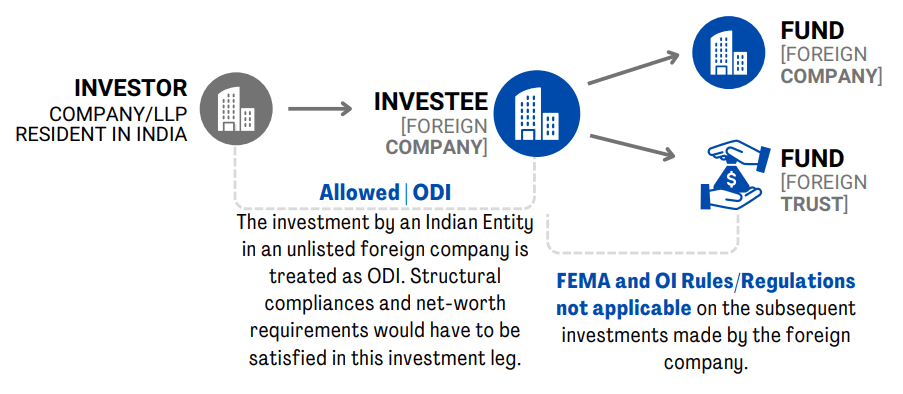
Indian entities, including companies, partnership firms, and LLPs, may also make investments into foreign funds organised as a company. However, as per the OI Rules, investments made by an Indian entity into a foreign fund organised as a trust are not allowed. The implications under FEMA and OI Rules, in cases where the resident entity directly invests in the fund, have been diagrammed as follows:
In cases where the investment is made indirectly through a foreign company, the investment is allowed under FEMA and OI Rules. The implications are as follows.
Conclusion
While the FEMA and OI Rules lay down a comprehensive regime for outbound investments made by resident individuals and entities, direct investments by Indian entities into foreign trusts have been restricted. This is primarily due to a lack of transparency in foreign trust structures and the absence of proper formal instruments signifying the ownership and beneficial interests of the parties.
The resident investors, individuals, and entities alike, would need to conform to reporting and other regulatory requirements such as net-worth criteria, limitation of liability and other structural conditions laid down in the OI Rules to remain fully compliant with Indian laws. The absence of such compliance would result in making the structure vulnerable to scrutiny by the Reserve Bank of India and the Directorate of Enforcement, wherein the remedial measures (including litigation, compounding, late submission fees etc.) could be time-consuming and costly and attract directions to wind up the structure resulting in greater economic losses.
Authored by the Editorial Team at Metalegal Advocates. The views expressed are personal and do not constitute legal opinion.
AUTHORED BY
More Insights

22 Jun 2026
8
Min Read
Claim Admission Is Not Debt Acknowledgement: Supreme Court on RP’s Role & Limitation under the IBC
Can admission of a claim by a Resolution Professional extend limitation under section 18 of the Limitation Act? In Shankar Khandelwal v. Omkara Asset Reconstruction Pvt. Ltd., the Supreme Court answered this question in the negative, holding that claim admission during CIRP is merely a statutory claim-verification process and not an acknowledgement of debt. The ruling clarifies the RP’s non-adjudicatory role and reinforces important principles governing limitation under the IBC.

06 Apr 2026
5
Min Read
Minority Exit under S. 66: The Supreme Court on Fairness, Valuation, and the Limits of Judicial Scrutiny
The Supreme Court’s ruling in Pannalal Bhansali v. Bharti Telecom Ltd. clarifies the contours of fairness under Section 66 of the Companies Act, 2013. It reinforces a market-based approach to valuation, affirms the permissibility of DLOM, and underscores judicial deference in the absence of oppression, marking a significant shift in minority exit jurisprudence.
12 Nov 2025
14
Min Read
A Bird’s Eye View of the Insolvency and Bankruptcy Framework for Personal Guarantors under the IBC with Recent Judicial Developments
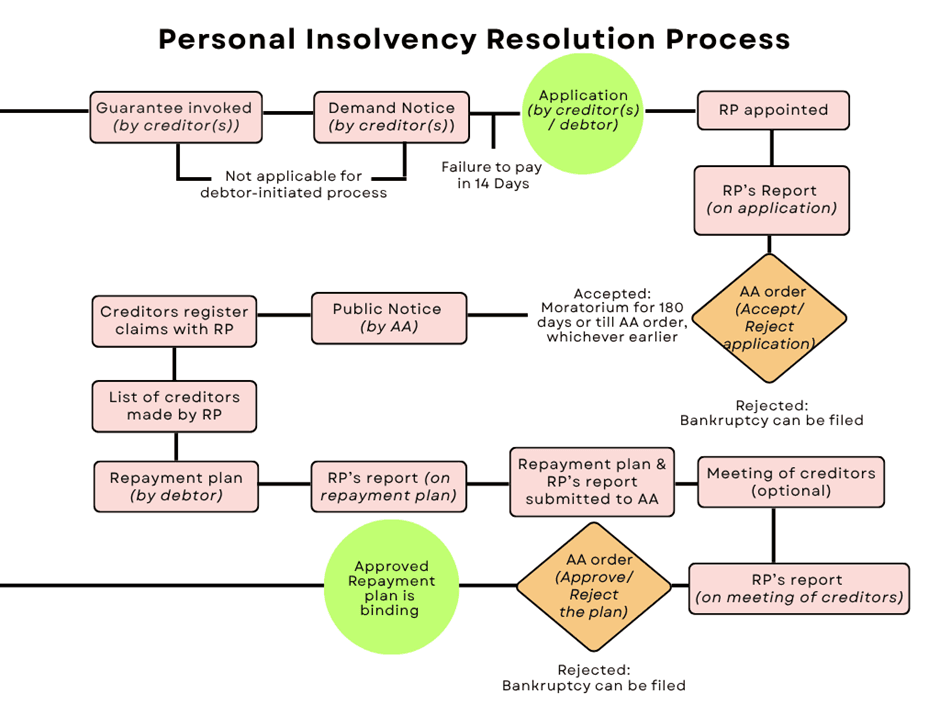
A concise overview of the personal insolvency and bankruptcy framework for personal guarantors under the IBC, with key NCLAT and NCLT rulings shaping the law. This piece explains initiation, moratoriums, repayment plans, creditor rights, bankruptcy triggers, and the 2025 Amendment Bill, offering a clear snapshot of the evolving jurisprudence and its practical implications for stakeholders.