
Introduction
The International Accounting Standards Board (‘IASB’) has issued a new standard, the International Financial Statement Reporting Standard 18 Presentation and Disclosure in Financial Statements (‘IFRS 18’). In India, IFRS is overseen by the Ministry of Corporate Affairs (‘MCA’), Government of India (‘GOI’), through the Institute of Chartered Accountants of India (‘ICAI’). IFRS 18 supersedes International Accounting Standards 1 (‘IAS 1’), which outlines the overall requirements for financial statements and will be effective for annual periods beginning on or after 01.01.2027. IFRS 18 aims to provide investors with transparent and accurate information about a company’s financial performance for future investments under the IFRS Accounting Standards[i]. This new standard will apply to all business entities using the IFRS Accounting Standards, whether public or private.
Background
The IASB issued IFRS 18 ‘Presentation and Disclosure in Financial Statements’ on 09.04.2024. This was to address the previous standards’ insufficient details of income and expenses. IFRS 18 includes three categories of income and expenses, two-income statement subtotals, and a single note on management performance measures. The evolution of IFRS 18 began in April 2016 with a Board Discussion, leading to a decision in May 2019 to publish an exposure draft. Thereafter, the exposure draft comment period was extended until September 2020. On 09.04.2024, IFRS 18 was officially issued. The objective of IFRS 18 is to ensure that all financial statements are prepared and presented according to IFRS accounting standards.
Key Changes in New Standard
1. Structured Statement of Profit or Loss
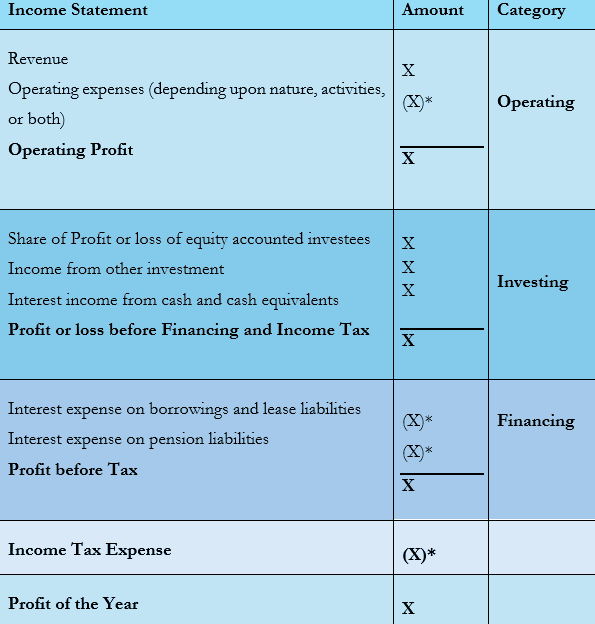
Under the previous regime, companies had the freedom to choose which subtotals they included, thereby creating inconsistency for investors when comparing financials across companies. The new standard mandates that companies adhere to a structured format for classifying income and expenses into three categories—operating, investing, and financing—and requires the inclusion of specific subtotals.[ii]
2. New Concept of Management-defined Performance Measures (‘MPM’)
This measure, also known as Alternative Performance Measures (‘APM’) or Non-GAAP Measures[iii], allows companies to use non-GAAP measures to explain their financial statements. The introduction of MPM represents a significant shift in financial reporting practices. MPMs are defined as subtotals of income and expenses; used in public communications with users of financial statements outside the financial statements and communicate management’s view of an aspect of an entity’s financial performance.
Companies need to elaborate in a single note to the financial statements, explaining the measure offers valuable information, detailing its calculation method, and reconciling it to an amount determined under IFRS accounting standards.
3. Guidance on Aggregation/Disaggregation
The new requirements for aggregation and disaggregation extend to primary financial statements, now encompassing newly defined roles, shared characteristics, and single dissimilar characteristics. In other words, it provides guidelines for determining line items in primary financial statements and note disclosures, discouraging the use of generic labels such as ‘other.’ Additionally, goodwill has been added as a new item in the balance sheet.
Conclusion
The new standard will be effective for annual reporting periods beginning on or after 01.01.2027, including for interim financial statements, whereby early adoption is also permitted. It is crucial for companies using IFRS to implement this standard and assess its potential impact on their financial statements. Transparent communication with investors about requirements is vital, ensuring clarity and changes required for future references. Furthermore, companies should evaluate how the new requirements will affect their financial reporting systems, making any necessary adjustments to ensure compliance. It is also important to stay aware of any local adjustments from this standard.[iv]
End Notes
[i] 161 taxmann.com 469 (Article)
[ii] Presentation and Disclosure in the Financial Statements - IFRS 18 (2024),
[iii] Non-GAAP financial measures are numerical indicators of a company’s historical or future financial performance, financial position, or cash flows. These measures adjust the most directly comparable GAAP (Generally Accepted Accounting Principles) figures by excluding certain items that the company believes are not good indicators of its performance.
[iv] How Companies Communicate Financial Performance is..., KPMG (09.04.2024),
https://kpmg.com/xx/en/home/insights/2024/04/presentation-and-disclosure-ifrs18.html
Authored by Siddharth Jha, Advocate at Metalegal Advocates. The views expressed are personal and do not constitute legal opinion.
More Insights

24 Feb 2026
12
Min Read
The Rise of Preventive Law and the Fear of Future Harm
This essay examines where preventive law has overreached: in compliance frameworks divorced from the actual causes of contraventions, in the systematic reversal of the burden of proof, and most acutely, in the routine deployment of provisional attachment as a pre-adjudicatory punishment. The law designed to address the fear of harm has itself become an object of fear. Preventive law has emerged as the legislature's response to the complexity, scale, and pace of modern business activity and, in jurisdictions like India, as a scaffolding for laws that lack organic social consensus.
30 May 2025
4
Min Read
Supreme Court: Retired Partner Still Liable under NI Act if Statutory Formalities Are Not Followed
The Supreme Court, in Shivappa Reddy v. S. Srinivasan, has reaffirmed that partners retiring from a firm must strictly comply with statutory requirements under the Partnership Act to escape liability under the Negotiable Instruments Act. The Court set aside a High Court order quashing proceedings and emphasised that non-compliance with Section 72 obligations leaves retired partners exposed to criminal liability for dishonoured cheques.

01 May 2025
6
Min Read
Unifying the Framework & Strengthening Oversight: RBI’s Draft 2025 Directions on Co-Lending Arrangements Explained
The RBI has released the Draft Co-Lending Arrangements Directions, 2025, proposing a unified, market-enabling framework for regulated entities. The draft aims to streamline risk-sharing, pricing, and borrower protections across digital and traditional lending partnerships while replacing fragmented earlier guidelines. This explainer highlights key provisions, compliance expectations, and systemic implications.