Glass-roofed atrium with repeating white arches

01 May 2024

DPIA Best Practices: From Recognition to Risk Mitigation

6

Min Read

Glass-roofed atrium with repeating white arches

01 May 2024

DPIA Best Practices: From Recognition to Risk Mitigation

6

Min Read

Glass-roofed atrium with repeating white arches

01 May 2024

DPIA Best Practices: From Recognition to Risk Mitigation

6

Min Read

Introduction

“Transparency breeds trust, and Data Protection Impact Assessments pave the path for both.”

In the digital landscape where data has emerged as a vital economic and strategic asset, safeguarding privacy has assumed unprecedented importance. A key instrument in this endeavour is the Data Protection Impact Assessment (‘DPIA’). This insight seeks to demystify the DPIA by exploring its definition, necessity, and advantages. Additionally, it examines procedural aspects and discusses the associated risks for individuals and corporations.

What is DPIA?

The DPIA is a systematic process employed by organisations to identify, assess, and mitigate the risks associated with processing personal data. This process becomes mandatory under the General Data Protection Regulation (‘GDPR’) in instances where data processing is likely to pose high risks to the rights and freedoms of data subjects. Such risks might include but are not limited to, data breaches and unauthorised access to personal information.

Further, a DPIA serves as an essential tool for organisations, ensuring compliance with data protection regulations and reinforcing the safeguarding of individual privacy. By conducting a DPIA, organisations can demonstrate accountability and proactive management of data protection risks.

When is DPIA Required?

The requirement for a DPIA becomes crucial in scenarios where data processing activities pose a significant risk to the rights and freedoms of individuals. This includes but is not limited to, large-scale processing of sensitive data, extensive surveillance activities, and handling data related to vulnerable groups such as children.

The proactive implementation of DPIAs enables organisations to not only comply with stringent data protection laws but also to pre-emptively identify and mitigate potential privacy issues. Through systematic risk evaluation, organisations demonstrate responsible data management, enhancing transparency and building trust with data subjects and the broader community.

In an era marked by increasing data breaches and regulatory scrutiny, prioritising DPIAs is a strategic decision. It represents a proactive stance towards privacy and cybersecurity, helping to avoid legal consequences and financial penalties. Moreover, integrating DPIAs into standard operational procedures showcases an organisation’s commitment to ethical data practices and the protection of individual privacy rights amidst ongoing digital and regulatory evolutions.

Advantages of DPIA:

  • ·  Risk Management and Compliance: Conducting DPIAs is a proactive approach that significantly bolsters an organisation’s risk management and compliance strategies. By identifying potential privacy risks early in the data processing lifecycle, DPIAs facilitate proactive risk mitigation, crucial for safeguarding individual rights while also ensuring regulatory compliance. This early intervention not only protects privacy but also minimizes the risk of legal consequences stemming from non-compliance.

  • ·  Enhancing Trust and Transparency: DPIAs play a crucial role in building trust among data subjects and stakeholders. By implementing safeguards and being transparent about the risk assessment process, organisations demonstrate their commitment to privacy protection. This transparency is further underscored by the requirement to document and, if necessary, share the DPIA process with supervisory authorities, thereby fostering internal and external confidence in the organisation’s data-handling practices.

  • ·  Informed Decision-Making and Innovation: Through comprehensive assessments of data processing operations, DPIAs provide organisations with valuable insights into potential risks and vulnerabilities. This holistic understanding is crucial for informed decision-making, enabling organisations to balance innovation with privacy protection. Consequently, DPIAs serve as a multifaceted tool, aiding in risk mitigation, ensuring legal compliance, building trust, and promoting transparency in the dynamic field of data protection.

DPIA Procedure:

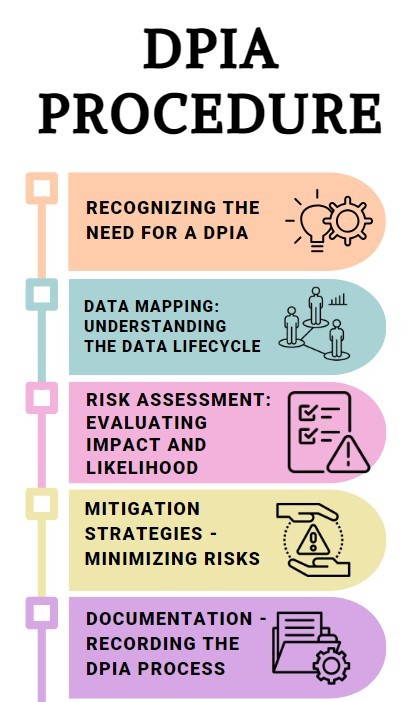
The procedure for completing a DPIA usually involves the following steps:
DPIA Best Practices
  • Recognising the Need for a DPIA: Organisations must assess whether a DPIA is required, taking into account the nature, scope, and potential risks of data processing activities. A DPIA is mandatory when there is a high likelihood of risk to individuals’ rights and freedoms due to data processing.

  • Data Mapping: Understanding the Data Lifecycle: This step involves defining the purpose of data processing, identifying the types of personal data involved, and understanding the potential impacts on individuals. A thorough data flow analysis helps in mapping the journey of personal data, including collection, storage, and sharing.

  • Risk Assessment: Evaluating Impact and Likelihood: Organisations are required to evaluate the potential risks to individuals’ rights, such as unauthorised access, data breaches, or discriminatory outcomes from algorithmic processing.

  • Mitigation Strategies - After assessing privacy risks, organisations should develop and implement effective measures to mitigate these risks. This step is essential for building trust and transparency and for the practical application of privacy safeguards in business operations.

  • Documentation - Recording the DPIA Process: Documenting the DPIA process is crucial for the early identification of potential privacy issues in a project. Comprehensive documentation also aids in ensuring compliance with the GDPR and other privacy regulations.

Risks to Individuals

DPIA Best Practices
  • Invasive Data Processing- Safeguarding Personal Privacy: Advances in data processing raise significant privacy concerns, including unauthorised access, data breaches, and risks from profiling or automated decision-making. The DPIA process is critical in identifying these threats and establishing robust safeguards. It ensures compliance with legal standards like the GDPR, protecting personal information and preserving privacy rights amid evolving data practices.

  • Potential Discrimination- Guarding Against Unfair Treatment: Data processing, especially through algorithms, can inadvertently lead to discrimination. The DPIA process is instrumental in detecting factors that might contribute to unfair treatment, such as biases in data or algorithms. By identifying and mitigating these risks, DPIAs help uphold fairness and promote unbiased data processing practices, in line with legal and ethical standards.

  • Loss of Control- Empowering Individuals Over Their Data: The DPIA process recognises the risk of individuals losing control over their data, a concern heightened by opaque processing practices. Addressing this issue, DPIAs advocate for transparency and provide mechanisms for individuals to exercise their rights, such as the right to information, rectification, and erasure under the GDPR. This approach ensures individuals retain significant control over their data, aligning with both legal requirements and ethical considerations.

Corporate Risks:

  • Reputational Damage- Impact on Brand Image: Reputational harm can significantly impact an organisation’s brand. DPIAs enable proactive identification and management of data processing risks that could damage reputation, such as privacy breaches. This preventive approach safeguards the brand and maintains stakeholder trust.

  • Legal Consequences- Fines and Penalties for Non-Compliance: Non-compliance with data protection laws, notably the GDPR, can result in substantial legal repercussions, including fines. DPIAs are instrumental in identifying compliance gaps and guiding corrective measures, thus helping organisations avoid financial penalties and maintain operational stability.

  • Business Disruption- Implications for Operations: DPIAs are crucial in identifying potential disruptions in business operations due to data processing challenges. By understanding and mitigating these risks, organisations can develop strategies to minimize operational disruptions, ensuring business continuity amidst evolving data protection landscapes.

  • Corporate Risk Mitigation Through DPIA- Overall, DPIAs serve as a strategic tool for comprehending and addressing corporate risks associated with data processing. This includes managing reputational risks, avoiding legal and financial penalties, and preventing operational disruptions. A comprehensive DPIA underscores an organisation’s commitment to responsible data handling, bolstering trust among stakeholders and consumers.

Compliance Risks:

  • Regulatory Consequences- Legal Ramifications for Non-Compliance: Not conducting a DPIA when needed can lead to significant regulatory consequences under laws like the GDPR. This includes fines and penalties imposed by authorities, legal actions, and complaints from individuals whose rights are infringed. Such non-compliance also risks damaging the organisation’s reputation among customers and stakeholders. Recognising these risks highlights the necessity of adhering to DPIA obligations to avoid legal repercussions.

  • Evolving Regulations- Staying Ahead of Shifting Data Protection Landscape: In the ever-changing domain of data protection, staying updated with regulatory changes is vital. Conducting DPIAs is a proactive approach to remain compliant with the evolving landscape. Regular assessments and adjustments of data processing activities in response to new regulations enable organisations to navigate legal complexities, ensuring ongoing compliance.

  • Global Perspectives- Navigating Cross-Border Compliance Challenges: With the global nature of data, organisations face the challenge of maintaining compliance across different jurisdictions. Conducting DPIAs is crucial for navigating cross-border compliance issues and adhering to international data protection standards. Understanding diverse regulatory frameworks and cultural contexts helps in implementing effective compliance strategies on a global scale.

  • Advantages of Completing a DPIA Under GDPR- Beyond being a regulatory mandate under the GDPR, completing a DPIA offers several advantages. It enables organisations to proactively identify and address privacy risks, ensuring adherence to data protection regulations. It also enhances transparency, minimizes legal risks, and helps protect the organisation’s reputation. Hence, DPIAs are not just a compliance requirement but a strategic necessity for organisations navigating the complex landscape of data protection.

Conclusion

In the realm of data protection, ignorance is not bliss—it is a liability waiting to happen. The implementation of a DPIA is indispensable for organisations in managing risks associated with data processing. DPIAs enable the systematic identification and mitigation of potential privacy risks, thus safeguarding individuals’ rights and freedoms. Beyond individual protection, DPIAs help organisations mitigate corporate risks, including reputational harm, financial penalties, and legal liabilities.

By adhering to DPIA requirements, organisations can avert compliance-related risks such as fines and legal actions, while also maintaining their reputational integrity. The DPIA process is not only a compliance mandate but also a strategic imperative in the current data-driven landscape. It offers a structured approach to assess and minimize data protection risks, aligning with both the legal obligations and ethical considerations of data processing.

Privacy is not a luxury; it is a fundamental right worth protecting through diligent assessment and proactive measures. As the complexities of data processing continue to evolve, the proactive adoption and thorough execution of DPIAs are crucial. They ensure regulatory compliance and reinforce an organisation’s commitment to upholding individual privacy. Embracing DPIA is, therefore, a strategic necessity, positioning organisations to navigate the intricate world of data protection effectively and responsibly.

Authored by Pratima Ajmera at Metalegal Advocates. The views expressed are personal and do not constitute legal opinion.

More Insights

Cover image for the article: Claim Admission is not Debt Acknowledgement: Supreme Court on RP’s Role & Limitation under the IBC

22 Jun 2026

8

Min Read

Claim Admission Is Not Debt Acknowledgement: Supreme Court on RP’s Role & Limitation under the IBC

Can admission of a claim by a Resolution Professional extend limitation under section 18 of the Limitation Act? In Shankar Khandelwal v. Omkara Asset Reconstruction Pvt. Ltd., the Supreme Court answered this question in the negative, holding that claim admission during CIRP is merely a statutory claim-verification process and not an acknowledgement of debt. The ruling clarifies the RP’s non-adjudicatory role and reinforces important principles governing limitation under the IBC.

Cover image for the article: Minority Exit under S. 66: The Supreme Court on Fairness, Valuation, and the Limits of Judicial Scrutiny

06 Apr 2026

5

Min Read

Minority Exit under S. 66: The Supreme Court on Fairness, Valuation, and the Limits of Judicial Scrutiny

The Supreme Court’s ruling in Pannalal Bhansali v. Bharti Telecom Ltd. clarifies the contours of fairness under Section 66 of the Companies Act, 2013. It reinforces a market-based approach to valuation, affirms the permissibility of DLOM, and underscores judicial deference in the absence of oppression, marking a significant shift in minority exit jurisprudence.

Cover image for the article: A Bird’s Eye View of the Insolvency and Bankruptcy Framework for Personal Guarantors under the IBC with Recent Judicial Developments

12 Nov 2025

14

Min Read

A Bird’s Eye View of the Insolvency and Bankruptcy Framework for Personal Guarantors under the IBC with Recent Judicial Developments

A concise overview of the personal insolvency and bankruptcy framework for personal guarantors under the IBC, with key NCLAT and NCLT rulings shaping the law. This piece explains initiation, moratoriums, repayment plans, creditor rights, bankruptcy triggers, and the 2025 Amendment Bill, offering a clear snapshot of the evolving jurisprudence and its practical implications for stakeholders.

Cover image for the article: Supreme Court Reiterates Strict Limitation Framework Under IBC: No Condonation Beyond 45 Days for Appeals Before NCLAT

19 May 2025

4

Min Read

Supreme Court Reiterates Strict Limitation Framework under IBC: No Condonation beyond 45 Days for Appeals before NCLAT

The Supreme Court, in Tata Steel Ltd. v. Raj Kumar Banerjee, reinforced the rigid limitation regime under the IBC by holding that appeals to the NCLAT must be filed within the prescribed 30-day window, with only a 15-day grace period allowed. The judgment underscores that even non-parties are bound by the statutory timeline, and tribunals cannot condone delays beyond this 45-day limit, ensuring procedural certainty and speed in insolvency proceedings.

Cover image for the article: Three-Fold Clarity from the Supreme Court under IBC: PUFE Transactions Distinguished, CoC Primacy Upheld, Participation of Superseded Directors Denied

24 Apr 2025

8

Min Read

Three-Fold Clarity from the Supreme Court under IBC: PUFE Transactions Distinguished, CoC Primacy Upheld, Participation of Superseded Directors Denied

The Supreme Court’s latest ruling in Piramal Capital v. 63 Moons offers critical jurisprudential clarity under the IBC. It distinguishes PUFE transactions from fraudulent trading, affirms the finality of CoC-approved resolution plans, and decisively holds that superseded directors have no participatory rights in CIRP. This judgment reaffirms the limited scope of judicial intervention and strengthens the commercial sanctity of insolvency resolution processes.

Cover image for the article: Post-Adjudication Compounding Rejected: Calcutta High Court Clarifies Scope Under FEMA

24 Apr 2025

4

Min Read

Post-Adjudication Compounding Rejected: Calcutta High Court Clarifies Scope under FEMA

This judgment by the Calcutta High Court settles a critical question under FEMA: can compounding be sought after an adjudication order is passed? The Court held that compounding is a pre-adjudication remedy and rejected the petitioner’s attempt to revive the option post-penalty. The decision reinforces the procedural integrity of FEMA and clarifies that contraveners must elect remedies in a time-bound and disciplined manner.

Cover image for the article: A First-of-its-Kind Ruling: Singapore High Court Recognises Indian CIRP under the UNCITRAL Model Law on Cross-Border Insolvency

17 Apr 2025

5

Min Read

A First-of-Its-Kind Ruling: Singapore High Court Recognises Indian CIRP under the UNCITRAL Model Law on Cross-Border Insolvency

The Singapore High Court recognised an Indian CIRP under the UNCITRAL Model Law. The ruling affirms India’s CIRP as a ‘foreign proceeding’, clarifies COMI principles, and establishes safeguards for Singapore-based creditors, paving the way for more robust cross-border insolvency cooperation.

Cover image for the article: NCLAT Clarifies: CoC’s Commercial Wisdom Not Fettered by Regulation 39(1A); Challenge Mechanism Optional, Not Compulsory

13 Apr 2025

4

Min Read

NCLAT Clarifies: CoC’s Commercial Wisdom Not Fettered by Regulation 39(1A); Challenge Mechanism Optional, Not Compulsory

The NCLAT has reaffirmed the commercial supremacy of the CoC in insolvency proceedings. The Tribunal clarified that Regulation 39(1A) of the CIRP Regulations limits only the resolution professional, not the CoC, and held that procedural mechanisms like the challenge process are facilitative, not mandatory. This judgment reinforces creditor autonomy and balances procedural compliance with commercial pragmatism.

Cover image for the article: Supreme Court Clarifies: Regulatory Penalties Not ‘Debt’ under Section 96 of the IBC

25 Mar 2025

4

Min Read

Supreme Court Clarifies: Regulatory Penalties Not ‘Debt’ under Section 96 of the IBC

The Supreme Court has clarified that regulatory penalties imposed under the Consumer Protection Act do not qualify as ‘debt’ under Section 96 of the IBC. This landmark ruling restricts the use of insolvency proceedings by errant developers to avoid penalties for non-compliance, reinforcing consumer rights and statutory accountability.

Cover image for the article: Reconciling PMLA with IBC: Tribunal Affirms ED’s Right to Attach Assets During CIRP

21 Mar 2025

4

Min Read

Reconciling PMLA with IBC: Tribunal Affirms ED’s Right to Attach Assets During CIRP

The Appellate Tribunal (SAFEMA) in SBI v. ED (2025) held that the moratorium under section 14 of the IBC does not bar enforcement proceedings under the PMLA. The decision reinforces that financial creditors cannot claim immunity under section 32A unless a resolution plan is approved. The ruling draws a clear boundary between civil insolvency resolution and criminal asset confiscation under anti-money laundering laws.

Cover image for the article: [AT SAFEMA, NEW DELHI] Tribunal Upholds FEMA Liability of Former Partners Despite Retirement Before Adjudication

19 Mar 2025

3

Min Read

[AT SAFEMA, NEW DELHI] Tribunal Upholds FEMA Liability of Former Partners Despite Retirement before Adjudication

The SAFEMA Appellate Tribunal upheld FEMA liability against former partners of Rosecut Diamonds for failure to realise export proceeds within the prescribed timeframe under GR forms. Despite their resignation prior to adjudication, the Tribunal held that the obligation under sections 7 and 8 of FEMA had crystallised during their tenure. The penalty was reduced, but liability was affirmed for non-compliance with foreign exchange regulations.

Cover image for the article: Statutory Demand v. Contractual Invocation: NCLAT Reiterates Rule in Personal Guarantor Insolvency

14 Mar 2025

4

Min Read

Statutory Demand v. Contractual Invocation: NCLAT Reiterates Rule in Personal Guarantor Insolvency

The NCLAT held that a statutory demand notice under Rule 7(1) of the 2019 IBC Rules does not amount to the invocation of a personal guarantee. The Tribunal reaffirmed that personal guarantor liability arises only when the guarantee is contractually invoked in accordance with its terms. This judgment reinforces procedural safeguards and curbs premature insolvency filings under s. 95 of the IBC.

Cover image for the article: IBC Prevails: The Supreme Court Restricts Premature Writs in Personal Insolvency Proceedings

13 Mar 2025

3

Min Read

IBC Prevails: The Supreme Court Restricts Premature Writs in Personal Insolvency Proceedings

SC sets aside High Court’s interference in IBC proceedings, affirming that insolvency disputes must follow statutory resolution channels.

Cover image for the article: NCLAT Affirms Secured Creditor Status Despite Non-Registration of Charge under the Companies Act

02 Mar 2025

5

Min Read

NCLAT Affirms Secured Creditor Status Despite Non-Registration of Charge under the Companies Act

The NCLAT has held that the absence of charge registration under the Companies Act, 2013 does not bar a creditor from being treated as a secured financial creditor under the IBC. The ruling underscores that commercial arrangements creating security—such as escrowed flats—remain valid during CIRP, reinforcing substance over statutory formality.

Cover image for the article: IBC v. PMLA: NCLT Affirms Jurisdictional Limits, Declines to Unfreeze ED-Attached Bank Account

27 Feb 2025

4

Min Read

IBC v. PMLA: NCLT Affirms Jurisdictional Limits, Declines to Unfreeze ED-Attached Bank Account

NCLT reaffirms that the IBC cannot override PMLA enforcement; RPs must approach the PMLA authority to unfreeze attached assets.

Cover image for the article: IBBI Notifies Amendments to CIRP Regulations to Strengthen Creditor Representation and Streamline Real Estate Resolution

09 Feb 2025

3

Min Read

IBBI Notifies Amendments to CIRP Regulations to Strengthen Creditor Representation and Streamline Real Estate Resolution

The IBBI’s 2025 amendments to the CIRP Regulations mark a pivotal reform in insolvency law—enabling early possession for homebuyers, formalising facilitator roles for large creditor classes, and mandating greater transparency in real estate projects. These changes aim to strengthen stakeholder representation, streamline the process, and build trust in insolvency proceedings.

Cover image for the article: IBC Overrides Tax Laws: NCLAT Declares Government Dues as Operational Debt

07 Feb 2025

2

Min Read

IBC Overrides Tax Laws: NCLAT Declares Government Dues as Operational Debt

NCLAT upholds IBC’s supremacy over tax laws, ruling that government tax dues do not qualify as secured debt in insolvency proceedings.

Cover image for the article: Literal v. Purposive Interpretation of Statutes: The Supreme Court, in a 2:1 Majority, Upholds Literal Interpretation of Section 31(4) of the IBC, With Dissent Favouring a Purposive Approach

06 Feb 2025

8

Min Read

Literal v. Purposive Interpretation of Statutes: The Supreme Court, in a 2:1 Majority, Upholds Literal Interpretation of Section 31(4) of the IBC, with Dissent Favouring a Purposive Approach

A Supreme Court ruling reignites the debate on literal vs. purposive statutory interpretation, shaping the future of insolvency law.

Cover image for the article: Bombay High Court Upholds: Settlement with Creditors Alone Cannot Justify a Stay on Liquidation Proceedings Under the Companies Act

03 Feb 2025

3

Min Read

Bombay High Court Upholds: Settlement with Creditors Alone Cannot Justify a Stay on Liquidation Proceedings under the Companies Act

The Bombay High Court rules that creditor settlements alone do not justify a liquidation stay under Section 466 of the Companies Act.

Cover image for the article: NCLT Mumbai: CIRP Application Dismissed Due to Pre-Existing Dispute and Bar Under Section 10A of the IBC

31 Jan 2025

3

Min Read

NCLT Mumbai: CIRP Application Dismissed Due to Pre-Existing Dispute and Bar under Section 10A of the IBC

NCLT Mumbai dismisses CIRP application, citing a pre-existing dispute and the Section 10A COVID-19 moratorium under the IBC.

Cover image for the article: Strict Interpretation of Section 101 of the IBC: NCLAT Says No Scope for Extending Moratorium Beyond 180 Days

30 Jan 2025

4

Min Read

Strict Interpretation of Section 101 of the IBC: NCLAT Says No Scope for Extending Moratorium beyond 180 Days

NCLAT rules that the moratorium under Section 101 of the Insolvency and Bankruptcy Code is mandatory and cannot exceed 180 days.

Cover image for the article: IBC Moratorium v. EPFO Claims: NCLAT Rejects Late Provident Fund Dues in CIRP Proceedings

21 Jan 2025

3

Min Read

IBC Moratorium v. EPFO Claims: NCLAT Rejects Late Provident Fund Dues in CIRP Proceedings

The NCLAT rules that EPFO’s late claims in insolvency cases are barred under the IBC moratorium, reinforcing finality in CIRP resolutions.

Cover image for the article: Understanding SEBI’s Circular on Shareholding Transfers: Exemptions for Immediate Relatives & Change in Control Implications

07 Jan 2025

4

Min Read

Understanding SEBI’s Circular on Shareholding Transfers: Exemptions for Immediate Relatives & Change in Control Implications

SEBI clarifies that shareholding transfers among immediate relatives do not constitute a change in control, ensuring market stability.

Cover image for the article: External Commercial Borrowings: Framework and Challenges

04 Jan 2025

12

Min Read

External Commercial Borrowings: Framework and Challenges

Explore the regulatory framework and challenges of ECBs, including key risks, approval routes, and compliance essentials.

Cover image for the article: NCLT: No Jurisdiction Under Section 95 of the IBC Without CIRP Against Corporate Debtor

02 Jan 2025

4

Min Read

NCLT: No Jurisdiction under Section 95 of the IBC without CIRP against Corporate Debtor

NCLT holds that in absence of CIRP against the corporate debtor, Section 95 proceedings against the personal guarantor are not maintainable.

Cover image for the article: IBC and Limitation Law: A Strict Interpretation of Creditor Rights

01 Jan 2025

4

Min Read

IBC and Limitation Law: A Strict Interpretation of Creditor Rights

NCLAT reinforces strict limitation rules under IBC, rejecting condonation pleas and upholding creditor autonomy in insolvency cases.

Cover image for the article: Supreme Court’s Interpretation of Financial Debt under the IBC

30 Dec 2024

4

Min Read

Supreme Court’s Interpretation of Financial Debt under the IBC

The Supreme Court clarifies financial debt under the IBC, recognising obligations in a Deed of Hypothecation as enforceable guarantees.

Cover image for the article: NCLAT Validates Differential Treatment of Operational Creditors in CIRP for Commercial Viability

27 Dec 2024

5

Min Read

NCLAT Validates Differential Treatment of Operational Creditors in CIRP for Commercial Viability

NCLAT confirms that operational creditors can be treated differently if justified by commercial rationale and compliant with IBC safeguards.

Cover image for the article: SEBI Introduces Specialized Investment Funds and Mutual Funds Lite: Key Amendments Explained

23 Dec 2024

4

Min Read

SEBI Introduces Specialized Investment Funds and Mutual Funds Lite: Key Amendments Explained

SEBI introduces Specialized Investment Funds and Mutual Funds Lite, enhancing flexibility, compliance, and investor protection frameworks.

Cover image for the article: NCLT: Corporate Governance Safeguards Under Section 388B of the Companies Act, 1956

18 Dec 2024

4

Min Read

NCLT: Corporate Governance Safeguards under Section 388B of the Companies Act, 1956

A landmark NCLT Hyderabad judgement examines corporate fraud claims and disqualifications under Section 388B of the Companies Act, 1956.