Introduction
The Competition Commission of India (‘CCI’) has recently introduced the CCI (Determination of Turnover or Income) Regulations, 2024[i]* *(‘Regulations’). These regulations, coming into effect from 06.03.2024, aim to provide clarity and uniformity in determining turnover or income for enterprises and individuals under the purview of the Competition Act, 2002 (‘Act’). Understanding these regulations is crucial for businesses and individuals operating within India’s competitive landscape.
Determination of Turnover or Income for Enterprises
For enterprises, turnover or income includes sales value and other operating revenue as per audited financial statements, excluding certain components such as other income, indirect taxes, trade discounts, and intragroup sales. Where consolidated financial statements are required under the Companies Act, 2013, the turnover shall be based on such statements. In the absence of audited financials, the turnover can be certified by a statutory auditor or a Chartered Accountant, supported by an affidavit. Foreign currency turnover should be converted to Indian rupees using specified criteria.
Determination of Income for Individuals
For individuals, income is deemed as the gross total income as per the income tax returns filed under the Income-tax Act, 1961, with specific exclusions for income from house property and capital gains. In instances where tax returns are absent or filed across multiple jurisdictions, a Chartered Accountant’s certification, supplemented by an affidavit, serves as the basis for income determination. Further, individuals not required to file income tax returns shall certify their total income through a Chartered Accountant, supported by an affidavit.
Removal of Difficulties
The regulations empower the CCI to address unforeseen situations or interpretational ambiguities not explicitly covered within the regulatory framework. Decisions regarding matters not addressed in these Regulations or their interpretation shall be made by the CCI, and such decisions shall be binding. This ensures flexibility and enables the CCI to resolve emerging turnover or income determination challenges promptly.
Conclusion
The Regulations represent a significant step towards streamlining the computation of turnover or income for entities and individuals subject to the Act. By providing clear guidelines and procedures, these regulations enhance transparency, consistency, and efficiency in the enforcement of competition law in India. Adherence to these regulations is crucial for enterprises and individuals to ensure compliance with the Act and to foster a competitive business environment conducive to innovation and consumer welfare.
End Note
[i] Notification No. B-14011/2/2024-ATD-II dated 06.03.2024.
Authored by Nitish Solanki, Advocate at Metalegal Advocates. The views expressed are personal and do not constitute legal opinion.
More Insights

22 Jun 2026
8
Min Read
Claim Admission Is Not Debt Acknowledgement: Supreme Court on RP’s Role & Limitation under the IBC
Can admission of a claim by a Resolution Professional extend limitation under section 18 of the Limitation Act? In Shankar Khandelwal v. Omkara Asset Reconstruction Pvt. Ltd., the Supreme Court answered this question in the negative, holding that claim admission during CIRP is merely a statutory claim-verification process and not an acknowledgement of debt. The ruling clarifies the RP’s non-adjudicatory role and reinforces important principles governing limitation under the IBC.

06 Apr 2026
5
Min Read
Minority Exit under S. 66: The Supreme Court on Fairness, Valuation, and the Limits of Judicial Scrutiny
The Supreme Court’s ruling in Pannalal Bhansali v. Bharti Telecom Ltd. clarifies the contours of fairness under Section 66 of the Companies Act, 2013. It reinforces a market-based approach to valuation, affirms the permissibility of DLOM, and underscores judicial deference in the absence of oppression, marking a significant shift in minority exit jurisprudence.
12 Nov 2025
14
Min Read
A Bird’s Eye View of the Insolvency and Bankruptcy Framework for Personal Guarantors under the IBC with Recent Judicial Developments
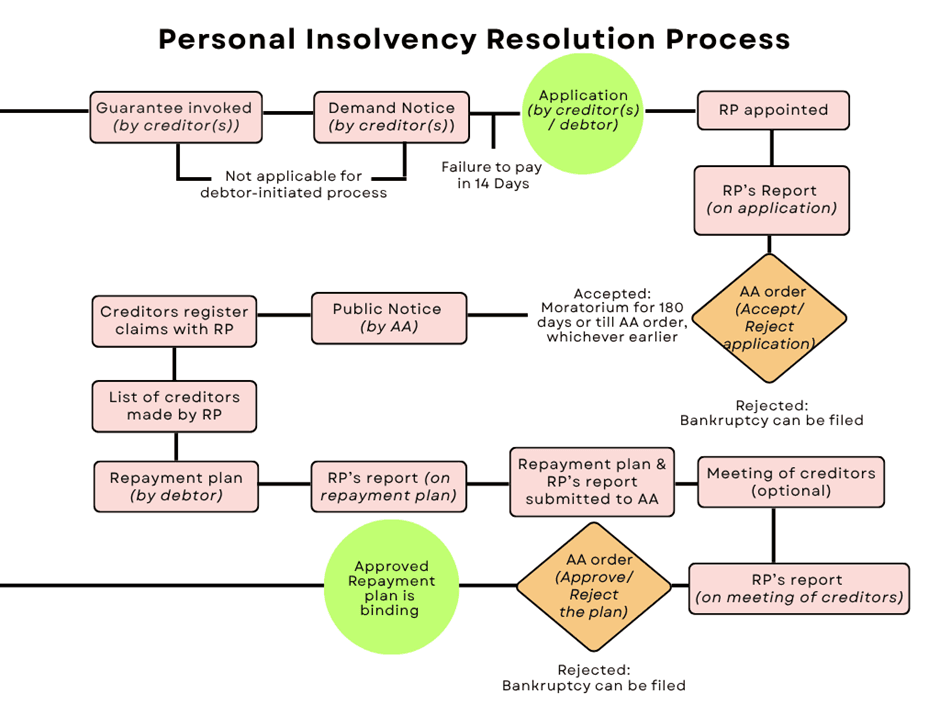
A concise overview of the personal insolvency and bankruptcy framework for personal guarantors under the IBC, with key NCLAT and NCLT rulings shaping the law. This piece explains initiation, moratoriums, repayment plans, creditor rights, bankruptcy triggers, and the 2025 Amendment Bill, offering a clear snapshot of the evolving jurisprudence and its practical implications for stakeholders.