Introduction
The National Financial Reporting Authority (‘NFRA’) has taken strong action against M/s M H Dalal & Associates, a renowned Chartered Accountancy firm, and its engagement partner, CA Devang Dalal in the recent case[i]. The NFRA's investigation revealed instances of professional misconduct and violations of both accounting and auditing standards, as well as non-compliance with the provisions of the Companies Act, 2013 (‘Act’). Consequently, significant penalties have been imposed, and CA Devang Dalal has been barred from performing certain roles within the financial ecosystem.
Brief Facts
M/s MAN Industries (India) Limited (‘MIIL’), a small-cap company based in Mumbai and listed on both BSE and NSE has had M/s M H Dalal & Associates as its statutory auditor since financial year (‘FY’) 2017-18 with CA Devang Dalal as the engagement partner for the FY 2020-21.
The NFRA initiated under s. 132(4) of the Act on M/s M H Dalal & Associates based on the information received from the Securities Exchange Board of India (‘SEBI’) regarding financial irregularities.
Preliminary examinations of MIIL’s financial statements for FY 2020-21 revealed several non-conformities with regulatory requirements during the preparation of these statements.
The auditors were requested to provide their audit file and Standard on Quality Control (SQC-1) policy. A thorough examination showed that the audit did not adequately address the relevant Standards on Auditing (‘SA’) and provisions of the Act.
The NFRA found that the auditor failed to apply professional judgment and scepticism during the audit, notably:
1. Omitting essential disclosures required by AS 24 related to sensitive transactions with related parties.
2. Providing inaccurate disclosures about the credit risk profile of trade receivables, contrary to AS 107 requirements.
3. Recording insufficient impairment losses for trade receivables, other assets, and investments in loans to subsidiaries.
4. Neglecting to verify physical inventories and related procedures managed by the company.
5. Failing to consider the relevant Indian Accounting Standard, Ind AS 115, and the associated fraud risks in revenue recognition.
6. Making false claims about the effectiveness of internal controls without sufficient testing, contrary to the Guidance Note of the ICAI.
7. Not obtaining sufficient appropriate audit evidence for material account balances and transaction classes, such as Trade Receivables.
Held
NFRA passed an order under s. 132 (4)(c) of the Act against the auditors based on the investigation conducted and held the auditors liable for professional misconduct and for contravening various sections of the Act.
NFRA imposed the following penalties:
M/s M H Dalal & Associates was fined Rs. 50,00,000.
CA Devang Dalal was debarred for 5 years from being appointed as an auditor or undertaking internal audits of any company or body corporate.
A penalty of Rs. 10,00,000 was imposed on CA Devang Dalal as he was serving as the statutory auditor.
Conclusion
The penalties imposed on M/s M H Dalal & Associates and CA Devang Dalal stress the grave consequences of failing to adhere to professional standards and ethical conduct within the auditing profession.
End Note
[i] Order No. 021/2023 dated 28.06.2023.
Authored by Nitish Solanki, Advocate at Metalegal Advocates. The views expressed are personal and do not constitute legal opinion.
More Insights

22 Jun 2026
8
Min Read
Claim Admission Is Not Debt Acknowledgement: Supreme Court on RP’s Role & Limitation under the IBC
Can admission of a claim by a Resolution Professional extend limitation under section 18 of the Limitation Act? In Shankar Khandelwal v. Omkara Asset Reconstruction Pvt. Ltd., the Supreme Court answered this question in the negative, holding that claim admission during CIRP is merely a statutory claim-verification process and not an acknowledgement of debt. The ruling clarifies the RP’s non-adjudicatory role and reinforces important principles governing limitation under the IBC.

06 Apr 2026
5
Min Read
Minority Exit under S. 66: The Supreme Court on Fairness, Valuation, and the Limits of Judicial Scrutiny
The Supreme Court’s ruling in Pannalal Bhansali v. Bharti Telecom Ltd. clarifies the contours of fairness under Section 66 of the Companies Act, 2013. It reinforces a market-based approach to valuation, affirms the permissibility of DLOM, and underscores judicial deference in the absence of oppression, marking a significant shift in minority exit jurisprudence.
12 Nov 2025
14
Min Read
A Bird’s Eye View of the Insolvency and Bankruptcy Framework for Personal Guarantors under the IBC with Recent Judicial Developments
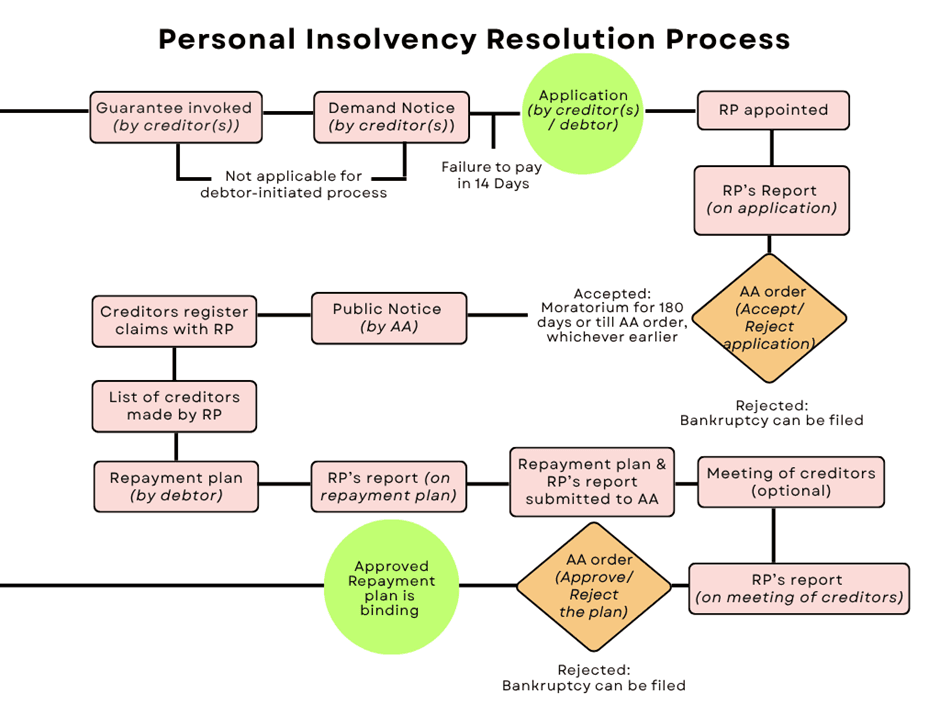
A concise overview of the personal insolvency and bankruptcy framework for personal guarantors under the IBC, with key NCLAT and NCLT rulings shaping the law. This piece explains initiation, moratoriums, repayment plans, creditor rights, bankruptcy triggers, and the 2025 Amendment Bill, offering a clear snapshot of the evolving jurisprudence and its practical implications for stakeholders.