Glass-roofed atrium with repeating white arches

22 Apr 2024

Arm’s Length Principle in Transfer Pricing: A Conceptual Analysis

8

Min Read

Glass-roofed atrium with repeating white arches

22 Apr 2024

Arm’s Length Principle in Transfer Pricing: A Conceptual Analysis

8

Min Read

Glass-roofed atrium with repeating white arches

22 Apr 2024

Arm’s Length Principle in Transfer Pricing: A Conceptual Analysis

8

Min Read

The arm’s length principle is the international standard for determining the taxability of profits resulting from transactions between related entities. This article analyses the principle's conceptual bases, its implementation, its role in preventing profit shifting, and compliance with global standards. The study contrasts arm’s length price with fair market value and details the methodologies for determining ALP. Additionally, it explores the interaction between transfer pricing, customs valuation, and FEMA pricing, addressing harmonization challenges.

I. Introduction

Arm’s length principle forms the bedrock of Indian (or, of most countries’) transfer pricing regulations. This principle is instrumental in ensuring that transactions between associated enterprises reflect market conditions as if the entities were independent and unrelated to each other, and the transactions between them take place only on pure commercial bases.

Within the Indian legal framework, the principle is enshrined in the Income-tax Act, 1961[i], laying down specific anti-avoidance rules in the form of transfer pricing provisions. These rules are aligned with global standards and address the challenges of shifting profits outside India. This article delves into the philosophical underpinnings, statutory bases, and practical implications of the arm’s length principle in the context of Indian transfer pricing law.

II. What is the Arm’s Length Principle?

The arm's length principle (‘Principle’) is the situation or condition that the parties to a transaction are acting independently of each other, and not subservient to any other interest. Such a transaction is called an arm’s length transaction, and the price at which it is affected is called the arm’s length price (‘ALP’).

The Principle dictates that the price in a transaction between related parties should be equivalent to the price that would have been charged between unrelated parties in an uncontrolled environment or manner. The Principle thus aims to ensure that intra-group transactions mirror those that would occur in a competitive market, thereby preserving the tax base of the jurisdictions involved. The Principle finds relevance not just in tax law but also in laws governing other aspects related to cross-border transactions, such as the Foreign Exchange Management Act, 1999 (‘FEMA’), where it is desired by the law that transactions should be carried out at an arm’s length price in order to control, conserve, and regulate the flow of foreign exchange.

In the context of international tax, the Principle finds its basis in Article 9 of the Model Tax Convention of the OECD[ii]. The Article states that where conditions are imposed between two related enterprises in their commercial or financial relations, which differ from those which would have been made between independent enterprises, profits should be determined ignoring such conditions – that is, profits which should have accrued to one party and which haven’t accrued because of such conditions should be included as profits of such party. Thus, the Principle finds its roots in transfer pricing law as well as international tax law.

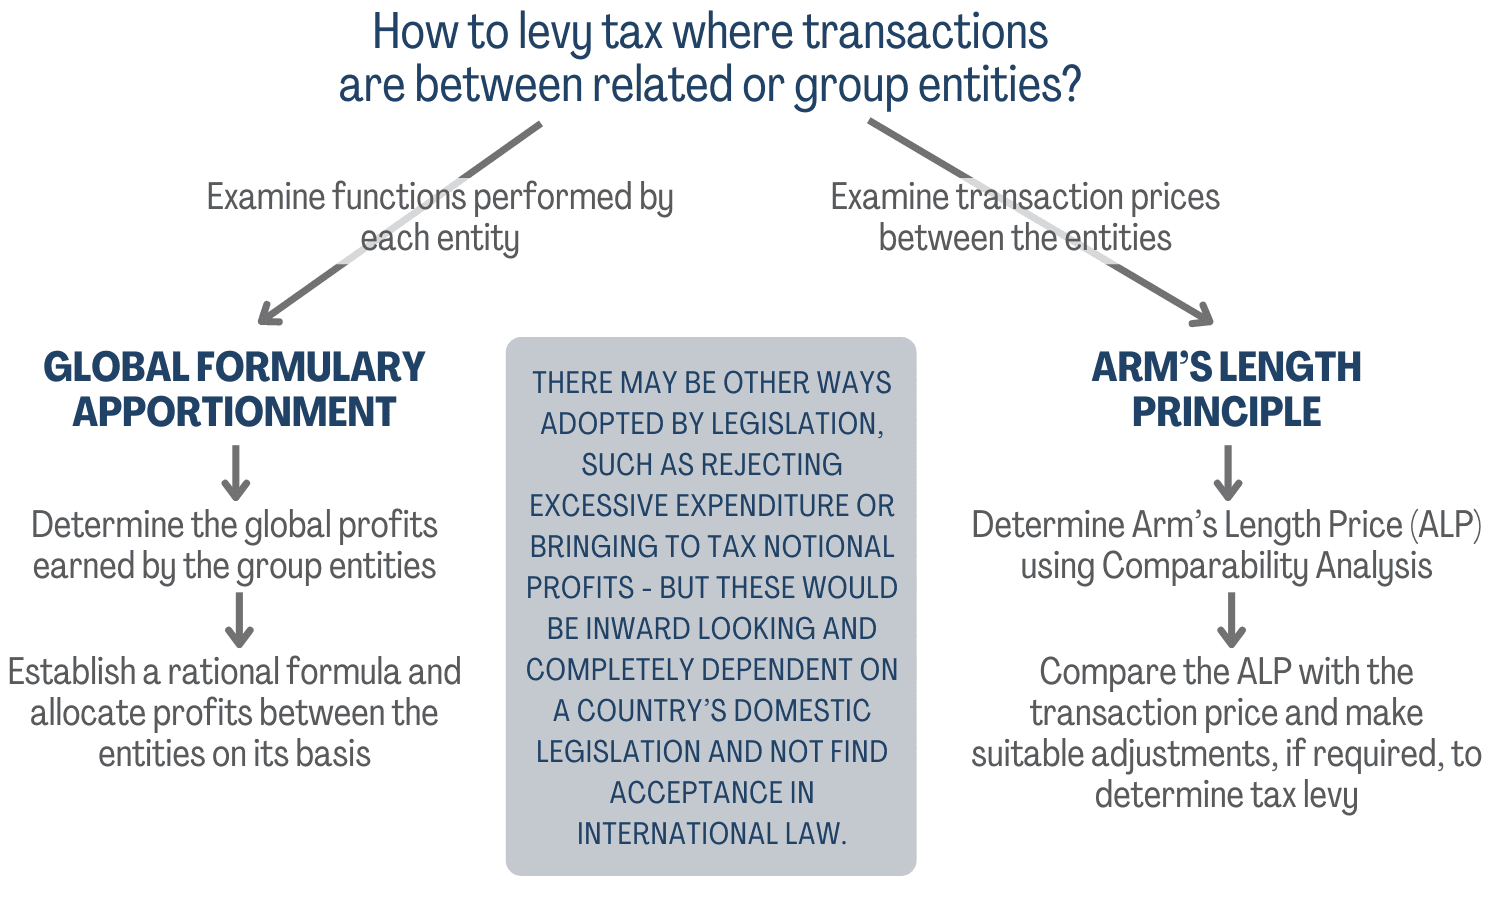
As an alternative to the Principle, another approach has been much deliberated in the international arena with respect to allocating profits between related enterprises. This approach termed Global Formulary Apportionment (‘GFA’), involves (i) determining the constituent units or entities who have transacted with each other, (ii) determining the global profits earned by these entities together, and (iii) establishing the formula to be used for allocating profits between the constituent entities (this could be on the basis of costs or assets or payroll or turnover or other similar variables). However, this method has largely been rejected as an alternative to the arm’s length principle.

Arm’s Length Principle in Transfer Pricing

III.  Arm’s Length Price v. Fair Market Value

The terms ‘arm’s length price’ and ‘fair market value’ (‘FMV’) are both used to assess the value of transactions and/or assets in different contexts, particularly in law, finance, and taxation. Although they may seem similar, they have distinct applications and implications.

From a contextual perspective, ALP is specifically used in the context of transfer pricing to regulate transactions and ensure that their value, for the purposes of tax computations, is considered appropriately. On the other hand, FMV is a broader concept used in various contexts other than tax, such as real estate, share valuations, and business valuations.

From a transactional perspective also, the two differ. While the ALP focuses on creating parity between controlled/related party transactions and uncontrolled transactions, FMV refers itself to open market value under uncontrolled conditions.

While ALP is statutorily computed based on prescribed methods (as would be discussed later) and not much flexibility is provided for in the computation, FMV is a generic computation used both in regulated as well as unregulated contexts. For instance, an immovable property purchase would require an FMV computation by the parties and this may be based on inquiries, bids from other prospective buyers, or even a mark-up added to the circle rate or stamp duty value of the property.

IV.   Core of the Principle: Comparability Analysis

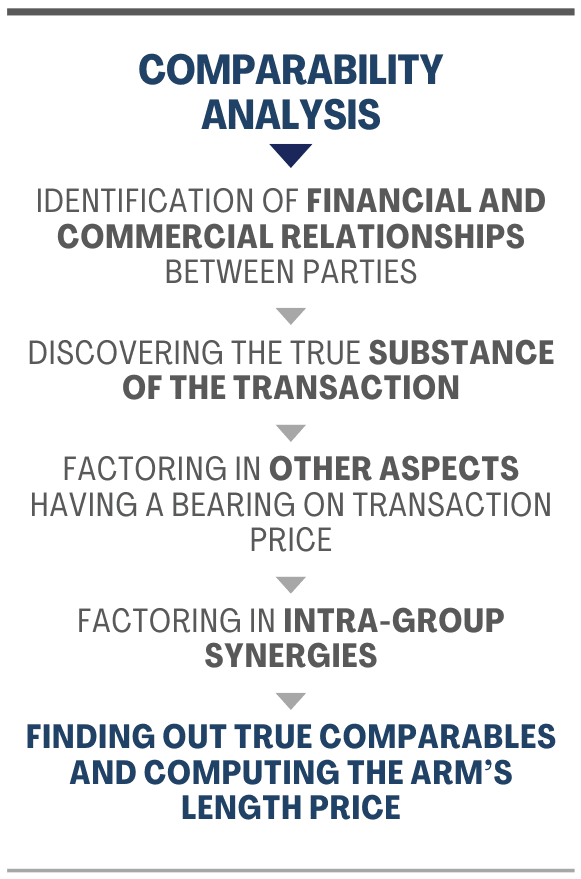
The end-result sought to be achieved by the application of the Principle is to determine the ALP. Constituting the heart and core of the Principle is comparability analysis. This involves a comparison of the conditions in a controlled transaction with the conditions that would have been made had the parties been independent and undertaking a comparable transaction under comparable circumstances. This involves a methodical approach and requires factoring in several aspects crucial for an accurate comparison.

Arm’s Length Principle in Transfer Pricing

Firstly, the identification of commercial and financial relationships between the parties has to be precisely done. This would require analysing the contractual terms of the transaction, carrying out an analysis of the functions performed by each party, and noting the characteristics and nature of the goods and services involved in the transaction. Further, differences in various markets and the business strategies involved (e.g., innovation, risk diversity, duration of arrangements etc.) have also to be taken into account.

Secondly, the actual transaction would have to be identified or discovered from written contracts as well as the conduct of the parties. In case the transaction, in its substance, differs from what has been spelt out in the written contract, the comparable transaction would differ. In short, the substance of the transaction has to be compared. For instance, a contract manufacturer may actually be and behave like an actual manufacturer if it assumes all risks in practice, and it should be compared with an actual manufacturer and command higher profit attribution.

Thirdly, other factors which have a significant bearing on price and business model should be taken into account – this would include analyses of losses, the effect of government policies, other duties and taxes, and local market features. These factors may vary over time and the comparison cannot be anachronistic.

Lastly, intra-group synergies play an important role in determining the actual price. Economies of scale and combinations of manpower and assets could exert a great influence on pricing across the lifecycle of the transaction. For instance, if goods are purchased in India and sold to group subsidiaries abroad, any volume discount that has been made available in India thus lowering the price, should be factored in. It may thus be found that the Indian entity is selling at less than the market price because of such a discount.

V.  Price Determination Methods

Comparability analysis involves a thorough examination of the terms and conditions of transactions between associated enterprises and comparing them to those between independent enterprises. The factors considered include the nature of the goods or services, contractual terms, market conditions, and business strategies. The primary methods endorsed by Indian law as well as international guidelines (e.g., the OECD guidelines on transfer pricing) include[iii]:

  • Comparable Uncontrolled Price (‘CUP’) Method: Prices in comparable transactions between unrelated parties are directly used. The comparison done here is directly between the prices of (i) the transaction under review, and (ii) another transaction between independent parties involving the same/similar goods or services.

  • Resale Price Method (‘RPM’): The price at which a product purchased from an associated enterprise is sold to an independent party is considered. The amount of profit retained by the reseller here is compared with other independent resellers.

  • Cost Plus Method (‘CPM’): The costs incurred by the supplier in a controlled transaction are marked up to arrive at an arm's length price.

  • Profit Split Method (‘PSM’): Profits from transactions are split based on how independent entities would have divided them under similar circumstances. This is generally done by identifying various functions performed by the constituent group entities and the profit split is determined based on who performed which function(s).

  • Transactional Net Margin Method (‘TNMM’): Net profit margins relative to an appropriate base (like costs or sales) are used to establish whether they are at arm’s length. Generally, this comparison is done at an entity or function level.

Though the most common statutorily prescribed method is to conduct a comparability analysis, other methods also find relevance in certain peculiar scenarios. As an example, one may say that if related parties have determined the consideration based on an international index (say, in a transaction involving the sale-purchase of coal), the price should be treated as the ALP. In India, there is a sixth method (the Other Method) that has also been prescribed – this is the residuary method, and it allows for any method which is rational and objective to be used for the determination of the ALP.

VI.  Interplay between Transfer Pricing, Customs Valuation, and FEMA Pricing

The convergence of transfer pricing with customs and FEMA regulations presents a complex interplay, as each framework has distinct objectives but overlapping concerns.

Customs authorities are concerned with the value of goods at the point of import or export to determine duties, while transfer pricing regulations aim to adjust prices between associated enterprises for tax purposes. While the true objective in both cases may be to determine the accurate arm’s length price of the transaction, the laws intend to work the opposite way.

Take, for instance, an import transaction where an Indian entity imports certain goods from its related group entity. Customs duty on imports would be higher if the price determined is higher. On the other hand, since the purchase price would be sought as a deduction while computing the profits of the Indian entity, the income-tax leviable would be higher if the price determined is lower. This contradictory approach often results in different valuations being arrived at by the two authorities.

Similarly, where FEMA prescribes that a transaction has to be carried out at a price in accordance with an internationally accepted pricing methodology, the arm’s length principle becomes squarely applicable. However, depending on whether the foreign exchange is coming into or leaving the country, the approach of authorities may differ, resulting in a contradictory outcome under the two laws.

While the arm’s length principle may be relevant for customs valuations or FEMA pricing, its application is where the two laws or authorities may differ. Harmonization between the statutory authorities – the Central Board of Direct Taxes (for income-tax or transfer pricing), the Central Board of Indirect Taxes and Customs (for customs duty), and the Directorate of Enforcement or Reserve Bank of India (for FEMA) – is the only practical way to resolution.

VII.  Conclusion

The arm’s length principle is the internationally accepted standard for determining the price at which related party or intra-group transactions should be carried out. It is notable that the principle does not prohibit such transactions but merely seeks to regulate them for the purpose of determining accurate profits which could be rightfully taxed in respective jurisdictions.

The Indian adoption of the Principle mirrors the international consensus and also factors in India-specific anti-avoidance rules to make the checks and balances robust. Various developments in global taxation frameworks, such as the OECD’s Base Erosion and Profit Shifting (‘BEPS’) actions, have influenced further refinements in the Indian transfer pricing regulations. The dynamic interplay between national legislation and global standards necessitates ongoing vigilance and adaptation, ensuring that the ALP remains effective in meeting both current and future challenges in international taxation.

End Notes

[i] Indian transfer pricing regulations are contained in sections 92 to 92F of the Income-tax Act, 1961.

[ii] Model Tax Convention prepared and issued by the Organization for Economic Co-operation and Development (OECD) forms the basis of bilateral tax treaties across the world. Similar model tax conventions have been issued by the United Nations (UN Model Tax Convention) and the United States of America (US Model Tax Convention).

[iii] Section 92C of the Income-tax Act, 1961 prescribes these methods.

Authored by the Editorial Team, Metalegal Advocates. The views expressed are personal and do not constitute legal opinion.
Portrait of Amar Gahlot

AUTHORED BY

Partner

Partner

Partner

More Insights

Cover image for the article: Claim Admission is not Debt Acknowledgement: Supreme Court on RP’s Role & Limitation under the IBC

22 Jun 2026

8

Min Read

Claim Admission Is Not Debt Acknowledgement: Supreme Court on RP’s Role & Limitation under the IBC

Can admission of a claim by a Resolution Professional extend limitation under section 18 of the Limitation Act? In Shankar Khandelwal v. Omkara Asset Reconstruction Pvt. Ltd., the Supreme Court answered this question in the negative, holding that claim admission during CIRP is merely a statutory claim-verification process and not an acknowledgement of debt. The ruling clarifies the RP’s non-adjudicatory role and reinforces important principles governing limitation under the IBC.

Cover image for the article: Minority Exit under S. 66: The Supreme Court on Fairness, Valuation, and the Limits of Judicial Scrutiny

06 Apr 2026

5

Min Read

Minority Exit under S. 66: The Supreme Court on Fairness, Valuation, and the Limits of Judicial Scrutiny

The Supreme Court’s ruling in Pannalal Bhansali v. Bharti Telecom Ltd. clarifies the contours of fairness under Section 66 of the Companies Act, 2013. It reinforces a market-based approach to valuation, affirms the permissibility of DLOM, and underscores judicial deference in the absence of oppression, marking a significant shift in minority exit jurisprudence.

Cover image for the article: A Bird’s Eye View of the Insolvency and Bankruptcy Framework for Personal Guarantors under the IBC with Recent Judicial Developments

12 Nov 2025

14

Min Read

A Bird’s Eye View of the Insolvency and Bankruptcy Framework for Personal Guarantors under the IBC with Recent Judicial Developments

A concise overview of the personal insolvency and bankruptcy framework for personal guarantors under the IBC, with key NCLAT and NCLT rulings shaping the law. This piece explains initiation, moratoriums, repayment plans, creditor rights, bankruptcy triggers, and the 2025 Amendment Bill, offering a clear snapshot of the evolving jurisprudence and its practical implications for stakeholders.

Cover image for the article: Supreme Court Reiterates Strict Limitation Framework Under IBC: No Condonation Beyond 45 Days for Appeals Before NCLAT

19 May 2025

4

Min Read

Supreme Court Reiterates Strict Limitation Framework under IBC: No Condonation beyond 45 Days for Appeals before NCLAT

The Supreme Court, in Tata Steel Ltd. v. Raj Kumar Banerjee, reinforced the rigid limitation regime under the IBC by holding that appeals to the NCLAT must be filed within the prescribed 30-day window, with only a 15-day grace period allowed. The judgment underscores that even non-parties are bound by the statutory timeline, and tribunals cannot condone delays beyond this 45-day limit, ensuring procedural certainty and speed in insolvency proceedings.

Cover image for the article: Three-Fold Clarity from the Supreme Court under IBC: PUFE Transactions Distinguished, CoC Primacy Upheld, Participation of Superseded Directors Denied

24 Apr 2025

8

Min Read

Three-Fold Clarity from the Supreme Court under IBC: PUFE Transactions Distinguished, CoC Primacy Upheld, Participation of Superseded Directors Denied

The Supreme Court’s latest ruling in Piramal Capital v. 63 Moons offers critical jurisprudential clarity under the IBC. It distinguishes PUFE transactions from fraudulent trading, affirms the finality of CoC-approved resolution plans, and decisively holds that superseded directors have no participatory rights in CIRP. This judgment reaffirms the limited scope of judicial intervention and strengthens the commercial sanctity of insolvency resolution processes.

Cover image for the article: Post-Adjudication Compounding Rejected: Calcutta High Court Clarifies Scope Under FEMA

24 Apr 2025

4

Min Read

Post-Adjudication Compounding Rejected: Calcutta High Court Clarifies Scope under FEMA

This judgment by the Calcutta High Court settles a critical question under FEMA: can compounding be sought after an adjudication order is passed? The Court held that compounding is a pre-adjudication remedy and rejected the petitioner’s attempt to revive the option post-penalty. The decision reinforces the procedural integrity of FEMA and clarifies that contraveners must elect remedies in a time-bound and disciplined manner.

Cover image for the article: A First-of-its-Kind Ruling: Singapore High Court Recognises Indian CIRP under the UNCITRAL Model Law on Cross-Border Insolvency

17 Apr 2025

5

Min Read

A First-of-Its-Kind Ruling: Singapore High Court Recognises Indian CIRP under the UNCITRAL Model Law on Cross-Border Insolvency

The Singapore High Court recognised an Indian CIRP under the UNCITRAL Model Law. The ruling affirms India’s CIRP as a ‘foreign proceeding’, clarifies COMI principles, and establishes safeguards for Singapore-based creditors, paving the way for more robust cross-border insolvency cooperation.

Cover image for the article: NCLAT Clarifies: CoC’s Commercial Wisdom Not Fettered by Regulation 39(1A); Challenge Mechanism Optional, Not Compulsory

13 Apr 2025

4

Min Read

NCLAT Clarifies: CoC’s Commercial Wisdom Not Fettered by Regulation 39(1A); Challenge Mechanism Optional, Not Compulsory

The NCLAT has reaffirmed the commercial supremacy of the CoC in insolvency proceedings. The Tribunal clarified that Regulation 39(1A) of the CIRP Regulations limits only the resolution professional, not the CoC, and held that procedural mechanisms like the challenge process are facilitative, not mandatory. This judgment reinforces creditor autonomy and balances procedural compliance with commercial pragmatism.

Cover image for the article: Supreme Court Clarifies: Regulatory Penalties Not ‘Debt’ under Section 96 of the IBC

25 Mar 2025

4

Min Read

Supreme Court Clarifies: Regulatory Penalties Not ‘Debt’ under Section 96 of the IBC

The Supreme Court has clarified that regulatory penalties imposed under the Consumer Protection Act do not qualify as ‘debt’ under Section 96 of the IBC. This landmark ruling restricts the use of insolvency proceedings by errant developers to avoid penalties for non-compliance, reinforcing consumer rights and statutory accountability.

Cover image for the article: Reconciling PMLA with IBC: Tribunal Affirms ED’s Right to Attach Assets During CIRP

21 Mar 2025

4

Min Read

Reconciling PMLA with IBC: Tribunal Affirms ED’s Right to Attach Assets During CIRP

The Appellate Tribunal (SAFEMA) in SBI v. ED (2025) held that the moratorium under section 14 of the IBC does not bar enforcement proceedings under the PMLA. The decision reinforces that financial creditors cannot claim immunity under section 32A unless a resolution plan is approved. The ruling draws a clear boundary between civil insolvency resolution and criminal asset confiscation under anti-money laundering laws.

Cover image for the article: [AT SAFEMA, NEW DELHI] Tribunal Upholds FEMA Liability of Former Partners Despite Retirement Before Adjudication

19 Mar 2025

3

Min Read

[AT SAFEMA, NEW DELHI] Tribunal Upholds FEMA Liability of Former Partners Despite Retirement before Adjudication

The SAFEMA Appellate Tribunal upheld FEMA liability against former partners of Rosecut Diamonds for failure to realise export proceeds within the prescribed timeframe under GR forms. Despite their resignation prior to adjudication, the Tribunal held that the obligation under sections 7 and 8 of FEMA had crystallised during their tenure. The penalty was reduced, but liability was affirmed for non-compliance with foreign exchange regulations.

Cover image for the article: Statutory Demand v. Contractual Invocation: NCLAT Reiterates Rule in Personal Guarantor Insolvency

14 Mar 2025

4

Min Read

Statutory Demand v. Contractual Invocation: NCLAT Reiterates Rule in Personal Guarantor Insolvency

The NCLAT held that a statutory demand notice under Rule 7(1) of the 2019 IBC Rules does not amount to the invocation of a personal guarantee. The Tribunal reaffirmed that personal guarantor liability arises only when the guarantee is contractually invoked in accordance with its terms. This judgment reinforces procedural safeguards and curbs premature insolvency filings under s. 95 of the IBC.

Cover image for the article: IBC Prevails: The Supreme Court Restricts Premature Writs in Personal Insolvency Proceedings

13 Mar 2025

3

Min Read

IBC Prevails: The Supreme Court Restricts Premature Writs in Personal Insolvency Proceedings

SC sets aside High Court’s interference in IBC proceedings, affirming that insolvency disputes must follow statutory resolution channels.

Cover image for the article: NCLAT Affirms Secured Creditor Status Despite Non-Registration of Charge under the Companies Act

02 Mar 2025

5

Min Read

NCLAT Affirms Secured Creditor Status Despite Non-Registration of Charge under the Companies Act

The NCLAT has held that the absence of charge registration under the Companies Act, 2013 does not bar a creditor from being treated as a secured financial creditor under the IBC. The ruling underscores that commercial arrangements creating security—such as escrowed flats—remain valid during CIRP, reinforcing substance over statutory formality.

Cover image for the article: IBC v. PMLA: NCLT Affirms Jurisdictional Limits, Declines to Unfreeze ED-Attached Bank Account

27 Feb 2025

4

Min Read

IBC v. PMLA: NCLT Affirms Jurisdictional Limits, Declines to Unfreeze ED-Attached Bank Account

NCLT reaffirms that the IBC cannot override PMLA enforcement; RPs must approach the PMLA authority to unfreeze attached assets.

Cover image for the article: IBBI Notifies Amendments to CIRP Regulations to Strengthen Creditor Representation and Streamline Real Estate Resolution

09 Feb 2025

3

Min Read

IBBI Notifies Amendments to CIRP Regulations to Strengthen Creditor Representation and Streamline Real Estate Resolution

The IBBI’s 2025 amendments to the CIRP Regulations mark a pivotal reform in insolvency law—enabling early possession for homebuyers, formalising facilitator roles for large creditor classes, and mandating greater transparency in real estate projects. These changes aim to strengthen stakeholder representation, streamline the process, and build trust in insolvency proceedings.

Cover image for the article: IBC Overrides Tax Laws: NCLAT Declares Government Dues as Operational Debt

07 Feb 2025

2

Min Read

IBC Overrides Tax Laws: NCLAT Declares Government Dues as Operational Debt

NCLAT upholds IBC’s supremacy over tax laws, ruling that government tax dues do not qualify as secured debt in insolvency proceedings.

Cover image for the article: Literal v. Purposive Interpretation of Statutes: The Supreme Court, in a 2:1 Majority, Upholds Literal Interpretation of Section 31(4) of the IBC, With Dissent Favouring a Purposive Approach

06 Feb 2025

8

Min Read

Literal v. Purposive Interpretation of Statutes: The Supreme Court, in a 2:1 Majority, Upholds Literal Interpretation of Section 31(4) of the IBC, with Dissent Favouring a Purposive Approach

A Supreme Court ruling reignites the debate on literal vs. purposive statutory interpretation, shaping the future of insolvency law.

Cover image for the article: Bombay High Court Upholds: Settlement with Creditors Alone Cannot Justify a Stay on Liquidation Proceedings Under the Companies Act

03 Feb 2025

3

Min Read

Bombay High Court Upholds: Settlement with Creditors Alone Cannot Justify a Stay on Liquidation Proceedings under the Companies Act

The Bombay High Court rules that creditor settlements alone do not justify a liquidation stay under Section 466 of the Companies Act.

Cover image for the article: NCLT Mumbai: CIRP Application Dismissed Due to Pre-Existing Dispute and Bar Under Section 10A of the IBC

31 Jan 2025

3

Min Read

NCLT Mumbai: CIRP Application Dismissed Due to Pre-Existing Dispute and Bar under Section 10A of the IBC

NCLT Mumbai dismisses CIRP application, citing a pre-existing dispute and the Section 10A COVID-19 moratorium under the IBC.

Cover image for the article: Strict Interpretation of Section 101 of the IBC: NCLAT Says No Scope for Extending Moratorium Beyond 180 Days

30 Jan 2025

4

Min Read

Strict Interpretation of Section 101 of the IBC: NCLAT Says No Scope for Extending Moratorium beyond 180 Days

NCLAT rules that the moratorium under Section 101 of the Insolvency and Bankruptcy Code is mandatory and cannot exceed 180 days.

Cover image for the article: IBC Moratorium v. EPFO Claims: NCLAT Rejects Late Provident Fund Dues in CIRP Proceedings

21 Jan 2025

3

Min Read

IBC Moratorium v. EPFO Claims: NCLAT Rejects Late Provident Fund Dues in CIRP Proceedings

The NCLAT rules that EPFO’s late claims in insolvency cases are barred under the IBC moratorium, reinforcing finality in CIRP resolutions.

Cover image for the article: Understanding SEBI’s Circular on Shareholding Transfers: Exemptions for Immediate Relatives & Change in Control Implications

07 Jan 2025

4

Min Read

Understanding SEBI’s Circular on Shareholding Transfers: Exemptions for Immediate Relatives & Change in Control Implications

SEBI clarifies that shareholding transfers among immediate relatives do not constitute a change in control, ensuring market stability.

Cover image for the article: External Commercial Borrowings: Framework and Challenges

04 Jan 2025

12

Min Read

External Commercial Borrowings: Framework and Challenges

Explore the regulatory framework and challenges of ECBs, including key risks, approval routes, and compliance essentials.

Cover image for the article: NCLT: No Jurisdiction Under Section 95 of the IBC Without CIRP Against Corporate Debtor

02 Jan 2025

4

Min Read

NCLT: No Jurisdiction under Section 95 of the IBC without CIRP against Corporate Debtor

NCLT holds that in absence of CIRP against the corporate debtor, Section 95 proceedings against the personal guarantor are not maintainable.

Cover image for the article: IBC and Limitation Law: A Strict Interpretation of Creditor Rights

01 Jan 2025

4

Min Read

IBC and Limitation Law: A Strict Interpretation of Creditor Rights

NCLAT reinforces strict limitation rules under IBC, rejecting condonation pleas and upholding creditor autonomy in insolvency cases.

Cover image for the article: Supreme Court’s Interpretation of Financial Debt under the IBC

30 Dec 2024

4

Min Read

Supreme Court’s Interpretation of Financial Debt under the IBC

The Supreme Court clarifies financial debt under the IBC, recognising obligations in a Deed of Hypothecation as enforceable guarantees.

Cover image for the article: NCLAT Validates Differential Treatment of Operational Creditors in CIRP for Commercial Viability

27 Dec 2024

5

Min Read

NCLAT Validates Differential Treatment of Operational Creditors in CIRP for Commercial Viability

NCLAT confirms that operational creditors can be treated differently if justified by commercial rationale and compliant with IBC safeguards.

Cover image for the article: SEBI Introduces Specialized Investment Funds and Mutual Funds Lite: Key Amendments Explained

23 Dec 2024

4

Min Read

SEBI Introduces Specialized Investment Funds and Mutual Funds Lite: Key Amendments Explained

SEBI introduces Specialized Investment Funds and Mutual Funds Lite, enhancing flexibility, compliance, and investor protection frameworks.

Cover image for the article: NCLT: Corporate Governance Safeguards Under Section 388B of the Companies Act, 1956

18 Dec 2024

4

Min Read

NCLT: Corporate Governance Safeguards under Section 388B of the Companies Act, 1956

A landmark NCLT Hyderabad judgement examines corporate fraud claims and disqualifications under Section 388B of the Companies Act, 1956.